If you rent in Dubai, you have probably asked: should I keep renting, or should I buy? The honest answer depends on your numbers and on how long you plan to stay. This guide compares the two step by step, using official fees and rules from the Dubai Land Department (DLD), the UAE Central Bank and DEWA, recent market data and one clear example. It is for people buying a home to live in, not to rent out.
The short answer
Buying usually costs more in the first few years, because you pay large one-off costs when you buy. Renting has much smaller costs at the start, but you pay rent every year and never get it back.
So the key question is: how many years will you stay? In our illustrative example below, owning becomes cheaper than renting after about seven years. With different inputs, that point moves.
What renting really costs each year
Rent is the biggest cost, but it is not the only one. Here are the main items a tenant pays.
Rent. In Q3 2026 (July to September), new apartment leases in Dubai had a median rent of AED 68,000 a year (DXB Interact analysis of Dubai Land Department records). Your rent will depend on the area, the building and the size of the home.
Agency fee. There is no fixed legal rate for agency fees in Dubai: the fee is whatever you agree in writing with a licensed broker. In practice, agencies commonly charge about 5% of the annual rent, often with a minimum of around AED 5,000, plus 5% VAT (Property Finder, 2026). This is market practice, not a legal cap.
Ejari. Registering a tenancy contract on Ejari costs about AED 178 online or AED 220 at a trustee centre (DLD).
Security deposit. Landlords can ask for a refundable security deposit; the law doesn't fix the amount. In our example we use 5% of the rent as an illustrative assumption. You should get it back at the end of the tenancy, so it is money tied up, not a cost.
DEWA. DEWA takes a refundable deposit of AED 2,000 for an apartment (AED 4,000 for a villa), plus about AED 155 in activation fees for a standard meter.
Moving. Moving costs vary, so we treat them as illustrative and leave them out, because renters and buyers both move in.
Rent can also go up when you renew. The rules are set by law, so read our guide on how rent increases work in Dubai before you plan your budget.
What owning really costs
When you buy, the costs come in two groups: money you pay once at the start, and money you pay every year.
One-off costs when you buy
Down payment. UAE Central Bank rules cap a first-home mortgage for UAE-resident expatriates at 80% of the property value up to AED 5 million (so at least 20% down), and 70% above AED 5 million. UAE nationals can borrow up to 85% and 75%. Off-plan homes are capped at 50%.
The table below shows the main fees on a ready apartment bought with a mortgage.
Cost | What it is | Source |
|---|---|---|
DLD registration fee | 4% of the sale value in total; 2% seller and 2% buyer by default | DLD |
DLD fixed fees | On a sale of AED 500,000 or more, about AED 4,720: a AED 4,000 trustee (service partner) fee plus 5% VAT, AED 250 for the title deed, AED 250 for the apartment or villa map, and AED 10 knowledge and AED 10 innovation fees | DLD |
Mortgage registration | 0.25% of the loan amount, plus small fixed fees and a trustee fee of AED 4,000 plus VAT | DLD |
Bank fees (example) | One UAE bank lists an arrangement fee of 1% of the loan (minimum AED 5,000) plus VAT, and a valuation fee of AED 2,625 | One UAE bank's published fees |
Buyer's agency fee | Agreed in writing with your broker; there is no fixed legal rate. For resale homes, agencies typically charge around 2% of the price plus 5% VAT, usually paid by the buyer | Market practice (Property Finder, 2026), not law |
DEWA deposit | Refundable AED 2,000 for an apartment, plus about AED 155 activation. Owners pay the deposit too, and DEWA refunds it only when the property is sold | DEWA |
If you are still choosing how to pay, our cash vs mortgage comparison explains the trade-offs.
Costs you pay every year
Mortgage interest. In November 2026, some UAE banks advertised home-loan rates starting from about 4% a year for short fixed periods (for example 3.99% and 4.14%, checked 12 November 2026). Variable rates follow the 3-month EIBOR benchmark, which was about 4.34% at the end of October 2026 (UAE Central Bank), plus the bank's margin. Your rate depends on the bank, the product and your profile. UAE mortgages can run for up to 25 years, and total debt repayments can't exceed 50% of income.
Only the interest part of your monthly payment is a true cost. The rest pays back the loan and builds your share of the home, so we don't count it as a cost. The home's value itself can go up or down.
Service charges. Every building has its own service charges for shared areas, security and upkeep. Real charges vary by building; check the building's figure in DLD's Service Charge Index (Mollak). There is no citywide average, so our example uses an illustrative figure.
Maintenance and home insurance. Repairs inside your home are your job. There is no official figure for these, so our example assumes 0.5% of the price a year for repairs inside the home (shared areas are covered by the service charge) and AED 1,000 a year for home insurance. These are assumptions, not quotes.
Money tied up in the down payment. That money could have stayed in savings, so we count the interest you give up as an illustrative assumption, not a promise of what savings would earn.
Worked example: rent vs buy over 3, 5 and 10 years
Illustrative example: an apartment bought at about AED 1.03 million versus renting at AED 68,000 a year.
In Q3 2026 (July to September), the median Dubai apartment sold for about AED 1.03 million, and new apartment leases had a median rent of AED 68,000 a year (DXB Interact analysis of Dubai Land Department records). The apartments sold and the apartments rented are different groups, so this is not the same home, and the numbers must not be read as a yield or a return. We use them only to build a simple example.
The inputs
Input | Value in the example | Type |
|---|---|---|
Purchase price | AED 1,027,620 (Q3 2026 median apartment sale price) | Reported market data (DXB Interact) |
Rent | AED 68,000 a year (Q3 2026 median new-lease apartment rent) | Reported market data (DXB Interact) |
Down payment | 20% = AED 205,524 | CBUAE cap for a first home (expat, under AED 5 million) |
Loan | AED 822,096 over 25 years | Loan length is an assumption |
Interest rate | 4.5% a year, fixed for the whole period | Assumption, not a quote |
DLD registration fee | 4% = about AED 41,100, all paid by the buyer | DLD rate (2% seller and 2% buyer by default). The example assumes the buyer pays all 4%; who pays is set in your sale agreement |
Other one-off buying costs | About AED 44,100 (DLD fixed fees, mortgage registration, one bank's fees, 2% agency fee plus VAT) | Mix of DLD fees, one bank's fees and a market-practice agency fee (Property Finder, 2026) |
Service charges | AED 15 per sq ft a year on 650 sq ft = AED 9,750 | Illustrative |
Maintenance | 0.5% of the price a year = about AED 5,100 (repairs inside the home only) | Illustrative assumption |
Home insurance | AED 1,000 a year | Illustrative |
Money tied up | 3% a year on the down payment = about AED 6,200 | Illustrative |
Renter's agency fee | AED 5,000 plus VAT, paid once (renter stays in one home) | Market practice (about 5%, minimum around AED 5,000) |
Ejari | About AED 178 each year | DLD |
Rent and price changes | None (both stay flat) | Assumption, not a forecast |
The results
Years you stay | Total cost of renting | Total cost of owning | Cheaper option in this example |
|---|---|---|---|
3 years | about AED 209,800 | about AED 258,700 | Renting, by about AED 48,900 |
5 years | about AED 346,100 | about AED 369,800 | Renting, by about AED 23,700 |
10 years | about AED 687,000 | about AED 629,300 | Owning, by about AED 57,700 |
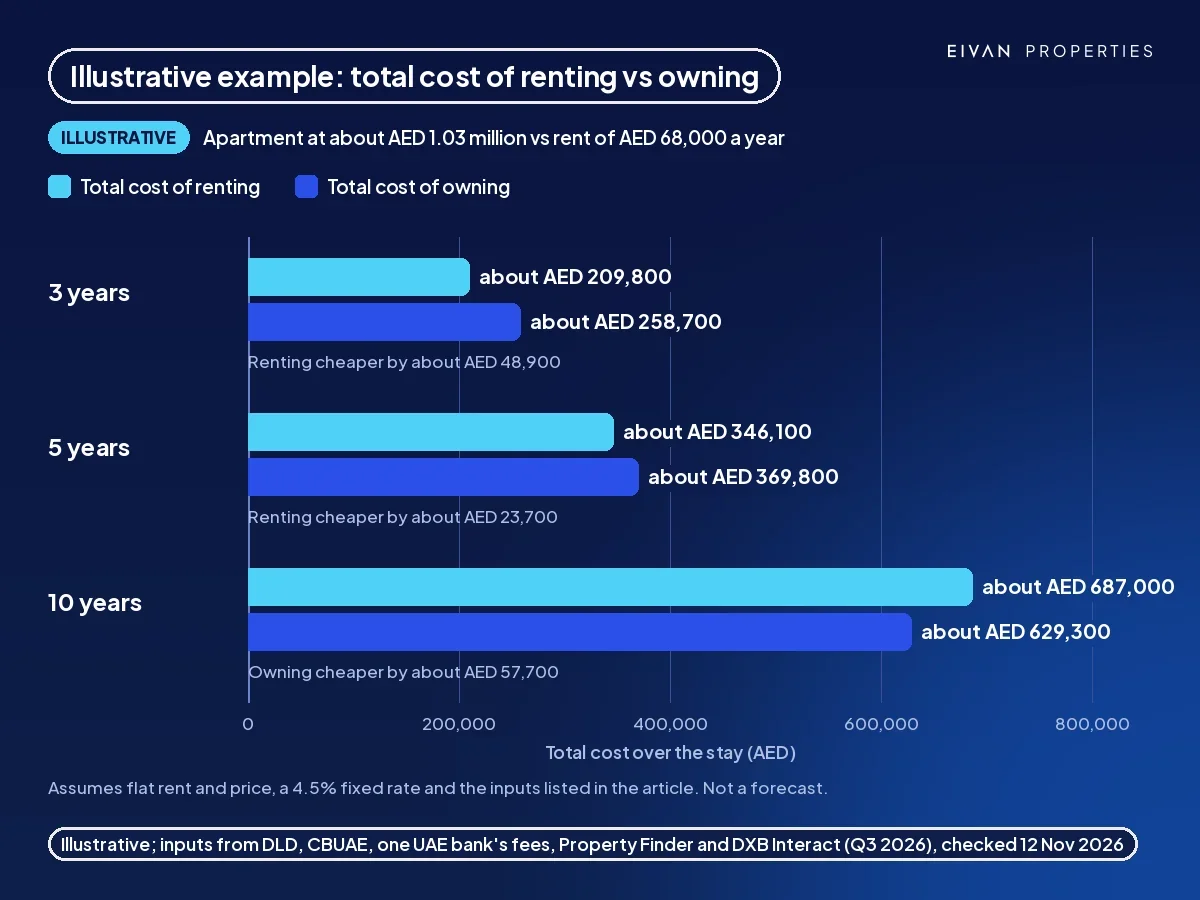
Under these assumptions, the break-even point is about seven years (between year 6 and year 7). After that, owning costs less, because the one-off costs are behind you and the interest falls as you repay the loan. The monthly mortgage payment would be about AED 4,570, against rent of about AED 5,670 a month. The result is sensitive to the assumptions: if maintenance were 1% of the price a year instead of 0.5%, owning would only become cheaper at about ten years in this example.
What this example leaves out
Price changes. We assume no rise or fall. If the value changes, the result changes.
Selling costs. Selling later adds costs and pushes break-even later.
Rent rises. Higher rent brings break-even sooner.
Rate changes. If your rate changes after a fixed period, your interest changes too. Our guide to fixed vs variable rates explains how this works.
When renting wins, and when buying wins
There is no single right answer. These points can help you decide.
Renting may suit you better if… | Buying may suit you better if… |
|---|---|
You may leave Dubai or change jobs within a few years | You plan to stay in the same home for many years |
Your income is not yet stable | Your income is stable and you have savings beyond the down payment |
You don't yet have the down payment plus the one-off costs | You can pay the down payment and the one-off costs without using your emergency fund |
You are not sure which area you want to live in | You know the area and the type of home you want |
Stay length matters most, because one-off costs need time to balance out. Job security matters because a mortgage is a long-term promise. Rate changes and the down payment's opportunity cost also shift the result.
The non-money side
Numbers are only part of the decision.
Flexibility. Renting lets you move more easily if your job, family or school needs change.
Stability. Owning means no landlord can decide not to renew, and you can change the home to suit your family.
Responsibility. As an owner, repairs inside the home are your job. As a tenant, many of them are the landlord's job.
FAQ
Is it better to rent or buy in Dubai?
It depends mainly on how long you will stay and on your own costs. In our illustrative example, renting was cheaper for the first six years or so, and owning was cheaper after about seven years. Run the numbers with your own rent, price and loan offer before you decide.
Should I rent or buy in Dubai if I might leave in two or three years?
Short stays usually favour renting, because one-off buying costs, such as DLD fees and agency fees, take years to balance out.
Is there a rent vs buy calculator for Dubai?
This article gives a worked example, not a calculator. Use the same steps: add up the one-off buying costs, then compare yearly renting costs with yearly owning costs.
Is the agency fee in Dubai always 5%?
No. There is no fixed legal rate for agency fees in Dubai: the fee is whatever you agree in writing with a licensed broker. About 5% is common market practice, not a legal cap.
Next steps
If buying looks right for you, the next step is to find out how much a bank will lend you. Read our guide to getting mortgage pre-approval, or talk to an adviser about what you can afford.
This article is general information, not financial, legal or tax advice. Your costs will depend on the home, the bank and your own situation. Check current fees and rates before you decide.
Figures checked on 12 November 2026.