How Much Down Payment to Buy Property in Dubai in 2026?
Many buyers ask the same question first: how much down payment to buy property in Dubai do you really need in 2026?
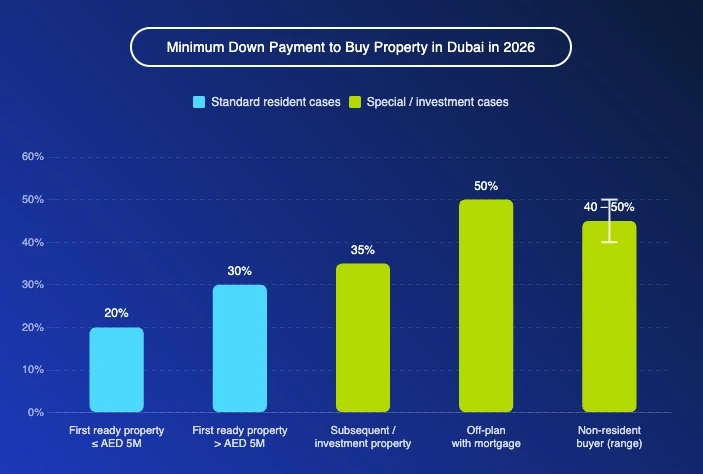
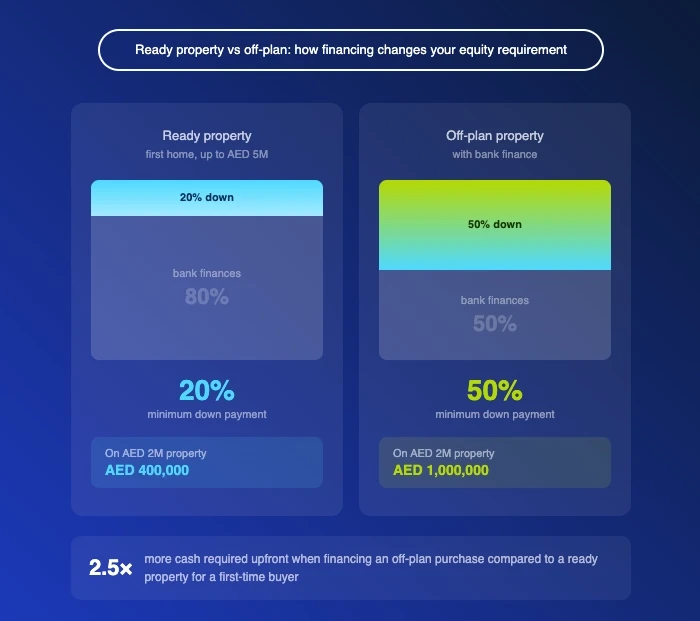
The short answer is this. For many expatriate buyers purchasing a first ready property worth up to AED 5 million, the minimum down payment is usually 20% of the property value. If the property price is above AED 5 million, that minimum typically rises to 30%. If you are buying an investment or subsequent property, the minimum down payment is usually 35%. If you are buying off plan with bank finance, the ceiling is stricter, and financing is capped at 50%, which means you may need at least 50% down. These caps come from the UAE Central Bank’s mortgage loan regulations.
That is the mortgage side. But the real answer is bigger than the down payment alone. In Dubai, buyers also need cash for transfer fees, registration fees, and mortgage registration costs. The Dubai Land Department sale registration fee is 4% of the sale value. For properties priced at AED 500,000 or more, the service partner fee is AED 4,000 plus VAT. DLD also lists a 0.25% mortgage registration fee on the mortgage value.
So, when buyers ask about the down payment to buy property in Dubai, the smart answer is: calculate both the lender’s minimum equity and the transaction cash you must pay upfront.
What is the minimum down payment to buy property in Dubai in 2026?
For 2026, the main benchmark for expatriate buyers comes from the UAE Central Bank mortgage rules:
Down payment to buy property in Dubai for ready properties
For an expatriate buyer buying a first home / owner occupied property:
Property value up to AED 5 million: bank financing can go up to 80%, so minimum down payment is 20%.
Property value above AED 5 million: bank financing can go up to 70%, so minimum down payment is 30%.
For an expatriate buyer buying a subsequent property or investment property:
Financing can go up to 65%, so minimum down payment is 35%.
For off
Financing can go up to 50%, so minimum down payment is at least 50%.
These are the regulatory caps. Banks can still apply tighter internal rules based on salary, residency status, credit profile, building eligibility, and property type.
How financing status changes the amount you need
This is where many buyers get caught off guard. Your financing status does change the cash you need.
Resident buyer with salary in the UAE
If you are a UAE resident and the property is a first ready home below AED 5 million, the market’s most common starting point is still the official 20% down payment because financing can reach 80%. Several UAE bank pages still market financing up to 80% for expatriates on eligible ready properties.
Non resident buyer
Non resident buyers often need more cash. Why? Because while the property can still be in a Dubai freehold area, many banks offer lower maximum financing for non residents than for resident salaried borrowers. For example, HSBC’s UAE non resident mortgage page says borrowers can obtain up to 60% financing, which means at least 40% down. ADCB advertises up to 50% financing for non residents, which means at least 50% down. That means the real world non resident range is often 40% to 50% down, depending on the lender and profile.
So, the financing status rule is simple:
Resident expat, first ready property up to AED 5 million: usually start with 20% down
Resident expat, first ready property above AED 5 million: usually start with 30% down
Investment or subsequent property: usually start with 35% down
Off plan with finance: usually start with 50% down
Non resident buyer: often prepare for 40% to 50% down, depending on the bank
What other cash do you need besides the down payment?
This is the part buyers must budget correctly.
The minimum cash required is not only your deposit. You should also plan for the official purchase costs payable during the transaction.
For a standard Dubai purchase, the core official items are:
DLD transfer fee: 4% of the property price
Service partner fee: AED 4,000 + VAT if the property value is AED 500,000 or more
Title deed issuance fee: AED 250
Apartment/villa map fee: AED 250
Knowledge fee: AED 10
Innovation fee: AED 10
Mortgage registration fee: 0.25% of the mortgage amount if you use financing
Because the user asked for consistent numbers, I am using these figures all the way through the article.
Worked examples: how much cash do you need?
Below are clear examples using the same numbers throughout.
Example 1: AED 1,000,000 ready property with a resident expat mortgage
For a first ready property up to AED 5 million, maximum financing is 80%. That means:
Property price: AED 1,000,000
Down payment: 20% = AED 200,000
Loan amount: AED 800,000
Now add the core official purchase costs:
DLD transfer fee: 4% = AED 40,000
Service partner fee: AED 4,000 + VAT. VAT at 5% on AED 4,000 is AED 200, so total AED 4,200.
Title deed fee: AED 250
Map fee: AED 250
Knowledge fee: AED 10
Innovation fee: AED 10
Mortgage registration fee: 0.25% of AED 800,000 = AED 2,000
Total minimum cash needed before any bank specific or broker specific extras = AED 246,720.
That is why buyers should never look at the down payment alone.
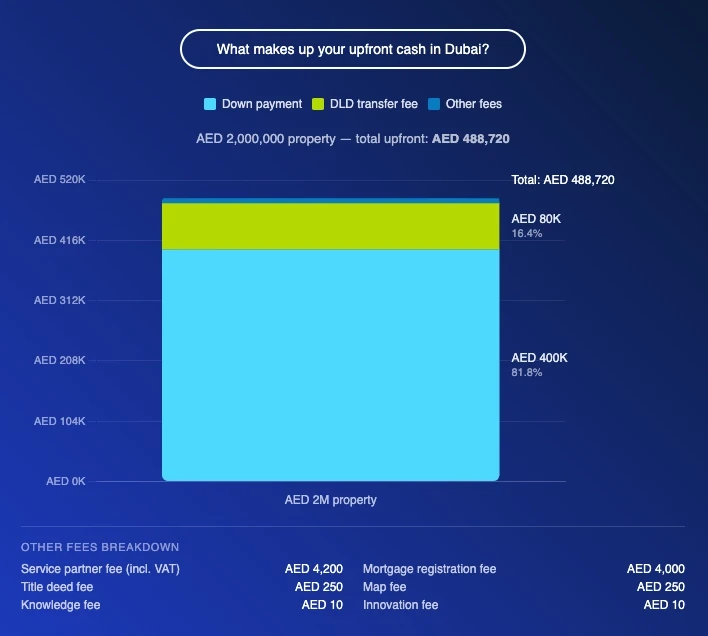
Example 2: AED 2,000,000 ready property with a resident expat mortgage
Property price: AED 2,000,000
Down payment: 20% = AED 400,000
Loan amount: AED 1,600,000
Official costs:
DLD transfer fee: AED 80,000
Service partner fee: AED 4,200
Title deed fee: AED 250
Map fee: AED 250
Knowledge fee: AED 10
Innovation fee: AED 10
Mortgage registration fee: 0.25% of AED 1,600,000 = AED 4,000
Total minimum cash needed before lender-specific extras = AED 488,720.
Example 3: AED 6,000,000 ready property for a first home
Because the price is above AED 5 million, financing for an expatriate first home is capped at 70%. That means the minimum down payment rises to 30%.
Property price: AED 6,000,000
Down payment: 30% = AED 1,800,000
Loan amount: AED 4,200,000
Official costs:
DLD transfer fee: AED 240,000
Service partner fee: AED 4,200
Title deed fee: AED 250
Map fee: AED 250
Knowledge fee: AED 10
Innovation fee: AED 10
Mortgage registration fee: 0.25% of AED 4,200,000 = AED 10,500
Total minimum cash needed before lender specific extras = AED 2,055,220.
How much down payment to buy property in Dubai off plan?
This depends on whether you are paying the developer directly or using bank finance.
Under the UAE Central Bank mortgage regulations, off plan schemes are capped at 50% financing. That means financed off plan buyers may need to fund at least 50% themselves.
In practice, many off plan projects are sold on developer payment plans rather than a traditional mortgage at the start. That changes the timing of the cash outlay, but not the fact that you must plan for a much higher equity contribution than a normal ready property mortgage.
So, for anyone asking about the down payment to buy property in Dubai on off plan stock, the safe planning rule is: prepare for materially higher upfront equity than a ready home mortgage.
What buyers usually forget
The biggest mistake is focusing on the bank approval and ignoring the closing cash.
Even when the loan covers 80% of the property value, the bank does not fund the DLD transfer fee. It also does not remove the mortgage registration fee. That means your real upfront cash requirement is:
Down payment + DLD transfer fee + service partner fee + title deed fee + map fee + knowledge fee + innovation fee + mortgage registration fee
That formula is what buyers should use in 2026. The exact structure of these official charges comes from Dubai Land Department service pages and the mortgage registration schedule.
How to reduce surprises before you buy
A strong buyer plan in Dubai usually has four steps.
1) Get mortgage pre approval first
Pre approval tells you whether the bank will treat you as a standard resident borrower or under tighter non resident rules. That single step can change your expected down payment from 20% to 40% or even 50% in some cases.
2) Separate property budget from cash budget
A buyer may be able to afford a AED 2 million property on monthly income, but still struggle with the nearly AED 488,720 minimum upfront cash shown in the example above.
3) Know whether the unit is ready or off plan
Ready properties can fit the 80% / 70% / 65% loan to value framework. Off plan financed purchases are a different case, with 50% financing cap under the mortgage rules.
4) Keep the numbers consistent
If you are budgeting today, keep using one set of official figures. For this article, those figures are:
4% DLD transfer fee
AED 4,000 + VAT service partner fee for sale value at or above AED 500,000
AED 250 title deed fee
AED 250 apartment/villa map fee
AED 10 knowledge fee
AED 10 innovation fee
0.25% mortgage registration fee on the mortgage amount
Final answer: how much down payment do you need to buy property in Dubai in 2026?
For most resident expatriate buyers, the starting point is:
20% down for a first ready property up to AED 5 million
30% down for a first ready property above AED 5 million
35% down for an investment or subsequent property
50% down for financed off plan purchases
40% to 50% down is a practical planning range for many non resident cases, depending on lender policy
But the better question is not only “what is the down payment?” It is “how much total cash do I need to close?”
That is the number that protects buyers from delays and failed transactions.
If you want to buy in Dubai in 2026, work with an agency that understands both property selection and financing structure. Eivan Properties, with more than 25 years of experience in Dubai real estate, can help you compare ready vs off plan options, estimate your full acquisition cost, and align your target property with your actual cash position. Explore opportunities at eivanproperties.ae.