Can You Get a Dubai Golden Visa With Off-Plan Property? Off Plan Golden Visa Dubai Eligibility Rules Explained
Dubai buyers ask this question all the time: can an off-plan purchase qualify for a Golden Visa, or do you need a completed property first?
The practical answer is yes, an off-plan purchase can qualify for an off plan Golden Visa Dubai case, but only when the investment meets the official value threshold and the buyer can show Dubai Land Department-recognized ownership evidence in their name. The core threshold used by Dubai authorities for the investor route is AED 2 million. Dubai Land Department’s investor Golden Visa service says the property purchase value must be AED 2 million or more at the time of purchase, and GDRFA states the investor must own a property or a group of properties with a total value of at least AED 2 million. GDRFA also says mortgaged property is acceptable and that the route includes all types of properties.
That matters for off-plan buyers because Dubai Land Department separately explains that initial registration covers properties purchased off-plan before they are transferred to the full real estate registry, and DLD also operates a service for developers to register off-plan units sold on the provisional register. Put together, the official framework shows that off-plan ownership can be formally registered in Dubai’s system before final title transfer. The Golden Visa service page itself requires the availability of an e-Certificate of Title / Title deed, so in real cases the key question is not “off-plan or ready,” but whether your off-plan purchase is properly recorded and supported by the ownership documents DLD will accept for the visa file. That is an inference based on the DLD and GDRFA service pages, and it is the safest way to explain the rule.
Off plan Golden Visa Dubai rules at a glance
For most buyers, the rule set is simpler than it looks.
First, the investment value must be AED 2 million or more. Dubai Land Department says that can be one property or more than one property under the applicant’s name. GDRFA says the same thing in broader form by allowing a property or a group of properties with a total value of at least AED 2 million.
Second, the ownership must be traceable to the applicant. DLD says the property must be wholly owned by the investor under the applicant’s name. If the ownership is a joint share, GDRFA says the applicant’s share itself must be worth at least AED 2 million. That is a very important point for married couples, siblings, or business partners buying together. A unit worth AED 2 million in total does not automatically qualify both co-owners. The qualifying test is the value of the individual recorded share.
Third, mortgaged purchases can still work. DLD says the property may be mortgaged, but the file must include a no-objection letter from the bank showing that the bank does not object to issuing the residence permit and setting out the paid amount and the balance. GDRFA also confirms that mortgaged property is acceptable.
Fourth, the application is handled as a Dubai investor Golden Visa process. DLD states the investor service is for a 10-year renewable residence permit, with a published service time of 7 to 10 business days, and it says the husband or wife, children, and parents can be sponsored.
Can off-plan property really qualify?
Yes, but this is where buyers need precision.
The official Dubai investor Golden Visa page does not use the words “off-plan only” or “ready only.” Instead, it sets the value threshold, asks for DLD-recognized ownership documents, and requires the property to be under the applicant’s name. GDRFA adds the strongest clue by saying the real estate route includes all types of properties. DLD’s separate FAQ and provisional registration service show that off-plan sales are legally registered in Dubai’s system before full title deed transfer. That is why the correct working interpretation is that off-plan property can qualify once the off-plan ownership is properly registered and the buyer can present the required DLD evidence.
So, in an off plan Golden Visa Dubai case, the real issue is documentation. Buyers should expect the file to be stronger when the unit is clearly recorded through DLD systems and the total qualifying value reaches AED 2 million. If there is financing, the bank NOC becomes part of that file.
What documents matter most for an off plan Golden Visa Dubai application?
Off plan Golden Visa Dubai documents buyers usually need
The DLD investor Golden Visa page lists these core documents for the applicant: passport, personal photo, UAE ID if any, current residence permit copy if any, and the availability of an e-Certificate of Title / Title deed. For mortgaged property, DLD also requires the bank no-objection letter showing the paid amount and the balance.
For off-plan buyers, the practical documentation stack usually needs to prove four things:
You are the recorded buyer in DLD systems.
The registered property value reaches AED 2 million.
The property is under your name alone, or your individual share alone reaches AED 2 million.
Any lender involved does not object to the residence permit.
Because DLD’s Golden Visa page specifically asks for an e-Certificate of Title / Title deed, off-plan investors should verify in advance which ownership output is accepted for their exact stage of purchase. DLD’s own system confirms that off-plan sales are registered on the provisional register, but buyers should still confirm the current acceptable document format before paying application fees. That is especially important where the unit is newly booked, still under construction, or recently transferred from booking to registered sale status.
The AED 2 million rule explained clearly
This is the number that controls the whole article, so it should stay clear and consistent.
The qualifying threshold is AED 2 million. DLD phrases it as the purchase value being AED 2 million or more at the time of purchase. GDRFA phrases it as owning a property or group of properties with a total value of no less than AED 2 million. In practice, this means buyers should not rely on vague marketing language, expected future appreciation, or a rough verbal estimate. The safest file is one where the DLD-recognized records clearly support the AED 2 million level.
That same clarity helps in edge cases:
If you combine more than one property, the total can reach AED 2 million.
If your property is mortgaged, it can still qualify, but the bank NOC is required.
If your purchase is jointly owned, your recorded share must itself reach AED 2 million.
Common mistakes buyers make with off-plan Golden Visa cases
A common mistake is assuming that any off-plan booking automatically creates Golden Visa eligibility. It does not. The transaction still needs to be formally recorded in a way that supports the visa file, and the value threshold still needs to be met. DLD’s own structure for off-plan initial registration shows that legal registration is central to protecting investor rights.
Another mistake is misunderstanding joint ownership. A couple may buy one unit worth AED 2 million, but if each spouse owns only a half share, that does not automatically mean each person qualifies. GDRFA says the share value in a joint property must not be less than AED 2 million for the applicant.
A third mistake is ignoring financing paperwork. DLD is clear that a mortgaged property can qualify only when the bank letter confirms the paid amount, the balance, and the bank’s no objection to issuing the residence permit.
Is off-plan a sensible route for Golden Visa investors?
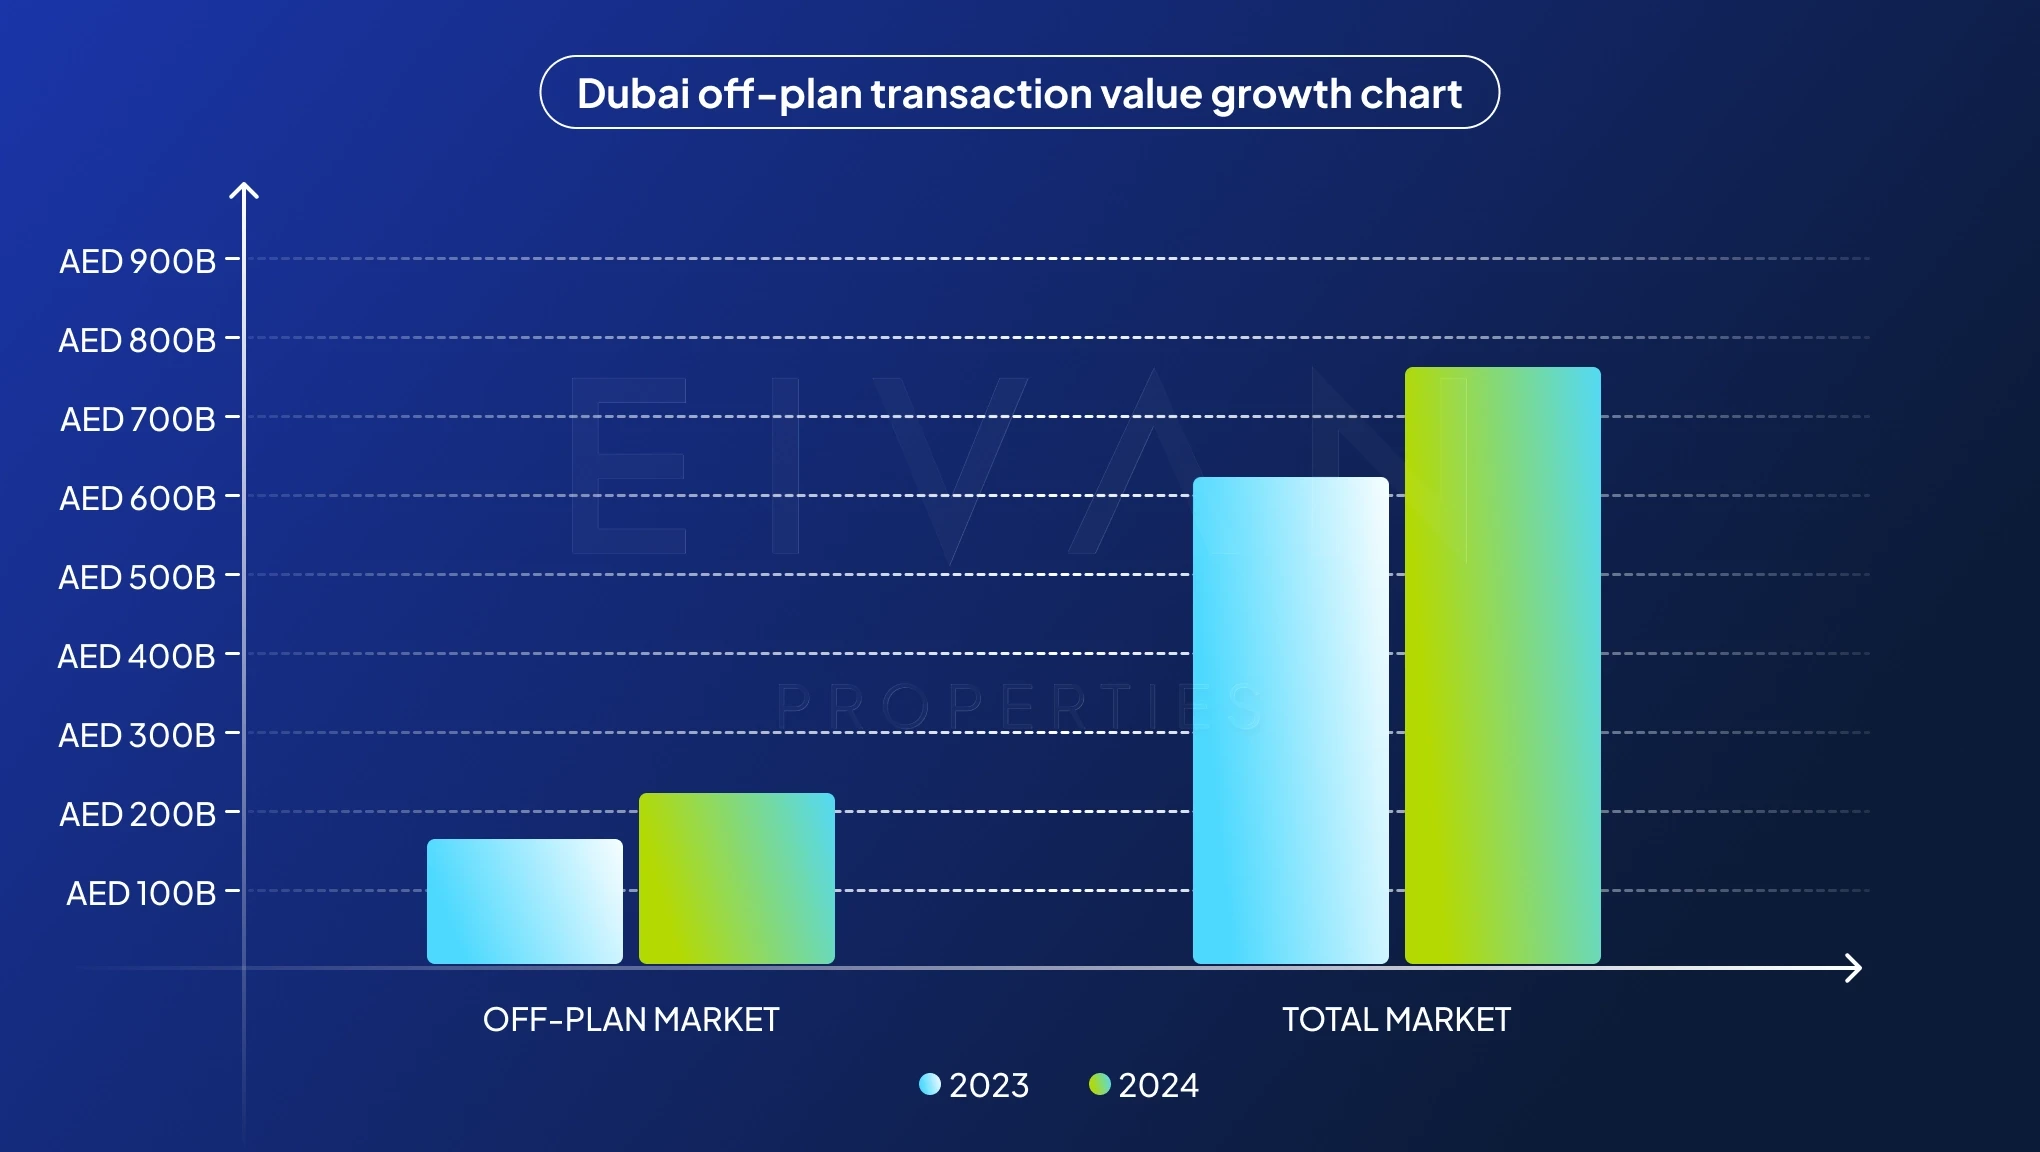
From a market perspective, off-plan has become a major part of Dubai demand. Dubai Land Department’s 2024 annual report shows off-plan transaction value reached AED 230.61 billion in 2024, up from AED 160.48 billion in 2023, which equals 43.70% year-on-year growth. Total market transaction value reached AED 760.99 billion in 2024, up 20.39% year on year. Those are not Golden Visa numbers, but they do show why so many buyers now ask about the off plan Golden Visa Dubai route. Off-plan is no longer a niche segment. It is one of the market’s biggest growth engines.
Still, visa eligibility should never be the only reason to buy. Buyers also need to review the developer, escrow structure, payment plan, completion timeline, contract transfer rules, and handover risk. Golden Visa potential is helpful, but asset quality still matters more over the long term.
Final answer: can you get a Dubai Golden Visa with off-plan property?
Yes, you can, but only when the case is structured correctly.
For an off plan Golden Visa Dubai application, the safest interpretation of the current Dubai rules is this: the buyer needs AED 2 million in qualifying property value, ownership evidence recognized by Dubai Land Department, the property recorded under the applicant’s name, and a bank NOC where financing is involved. DLD’s investor service is a 10-year renewable residence permit in Dubai, and the published process says the applicant must be inside the UAE when applying.
That means buyers should treat off-plan eligibility as a documentation and structuring issue, not just a marketing promise. Before committing, verify the registration status, your recorded ownership share, the exact DLD document you will use, and whether your total qualifying value reaches AED 2 million on the official records.
For buyers who want to structure this correctly from day one, Eivan Properties can help review the project, developer, paperwork path, and visa-readiness of the transaction. Eivan Properties has more than 25 years of experience in Dubai real estate, and you can explore their services at eivanproperties.ae.